01
MEMBER SUBMITS ENQUIRY
Members complete a guided 20 question intake covering the borrower, business, and purpose of the loan
FINANCEWERX
Ruby Loans transforms SME enquiries into structured, decision ready applications, creating a faster, simpler experience for borrowers while reducing manual intake and keeping lending decisions with your team
CONNECT WITH OUR TEAM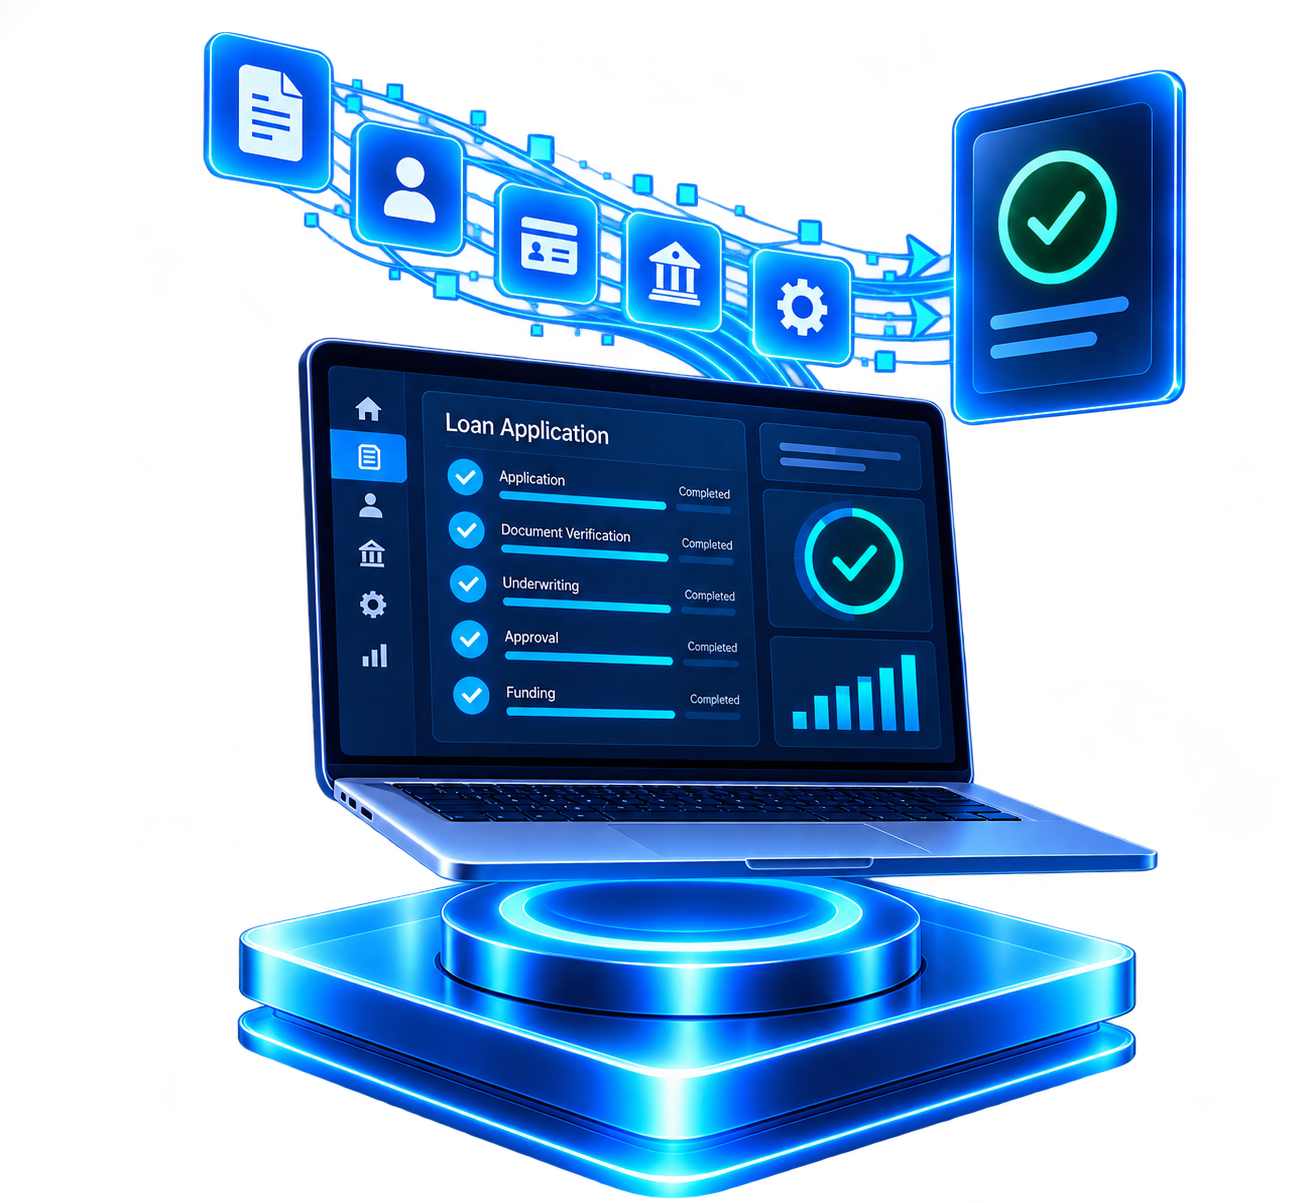
FINANCEWERX
Ruby Loans transforms SME enquiries into structured, decision ready applications, creating a faster, simpler experience for borrowers while reducing manual intake and keeping lending decisions with your team
RUBY LOANS
Ruby Loans guides members through a focused digital intake, validates information against your institution’s credit policy, organizes supporting documents, and prepares a structured application for lender review
Up to 80% of a typical SME lending application can be completed before it reaches the lending officer, allowing your team to focus on judgment and member relationships rather than building the file
01
Members complete a guided 20 question intake covering the borrower, business, and purpose of the loan
02
Ruby checks the information against your credit policy and risk appetite, identifies exceptions, and determines what should proceed
03
Financials, T2s, credit bureau information, and supporting documents are collected, classified, validated, and organized into a complete lending file
04
Your lending officer receives a structured application summary with the information needed to advance, request more information, or decline while keeping the final lending decision with your team
RUBY LOANS
Ruby Loans guides members through a focused digital intake, validates information against your institution’s credit policy, organizes supporting documents, and prepares a structured application for lender review
Up to 80% of a typical SME lending application can be completed before it reaches the lending officer, allowing your team to focus on judgment and member relationships rather than building the file
01
Members complete a guided 20 question intake covering the borrower, business, and purpose of the loan
02
Ruby checks the information against your credit policy and risk appetite, identifies exceptions, and determines what should proceed
03
Financials, T2s, credit bureau information, and supporting documents are collected, classified, validated, and organized into a complete lending file
04
Your lending officer receives a structured application summary with the information needed to advance, request more information, or decline while keeping the final lending decision with your team
Ruby Loans adapts to the way your credit union already lends, with configurable credit criteria and risk appetite, deployment under your own brand, and output designed to work with your existing LOS or core banking environment
Your institution retains control of lending policy, underwriting limits, and the member relationship while Ruby brings greater structure to the
application process
Works with your existing LOS or core banking platform
Institution-defined credit parameters, risk appetite, and underwriting limits
Borrower information and supporting documents for lender review
White-label, configurable to the institution, and designed for Canadian credit unions
Ruby Loans adapts to the way your credit union already lends, with configurable credit criteria and risk appetite, deployment under your own brand, and output designed to work with your existing LOS or core banking environment
Your institution retains control of lending policy, underwriting limits, and the member relationship while Ruby brings greater structure to the application process
Works with your existing LOS or core banking platform
Institution-defined credit parameters, risk appetite, and underwriting limits
Borrower information and supporting documents for lender review
White-label, configurable to the institution, and designed for Canadian credit unions
Ruby Loans standardizes how SME applications are gathered, assessed, and prepared so critical lending knowledge is embedded in the process rather than dependent on individual staff or informal practices
This supports continuity as teams change, strengthens lending discipline, and creates a more reliable process as SME portfolios grow
BOOK A DEMO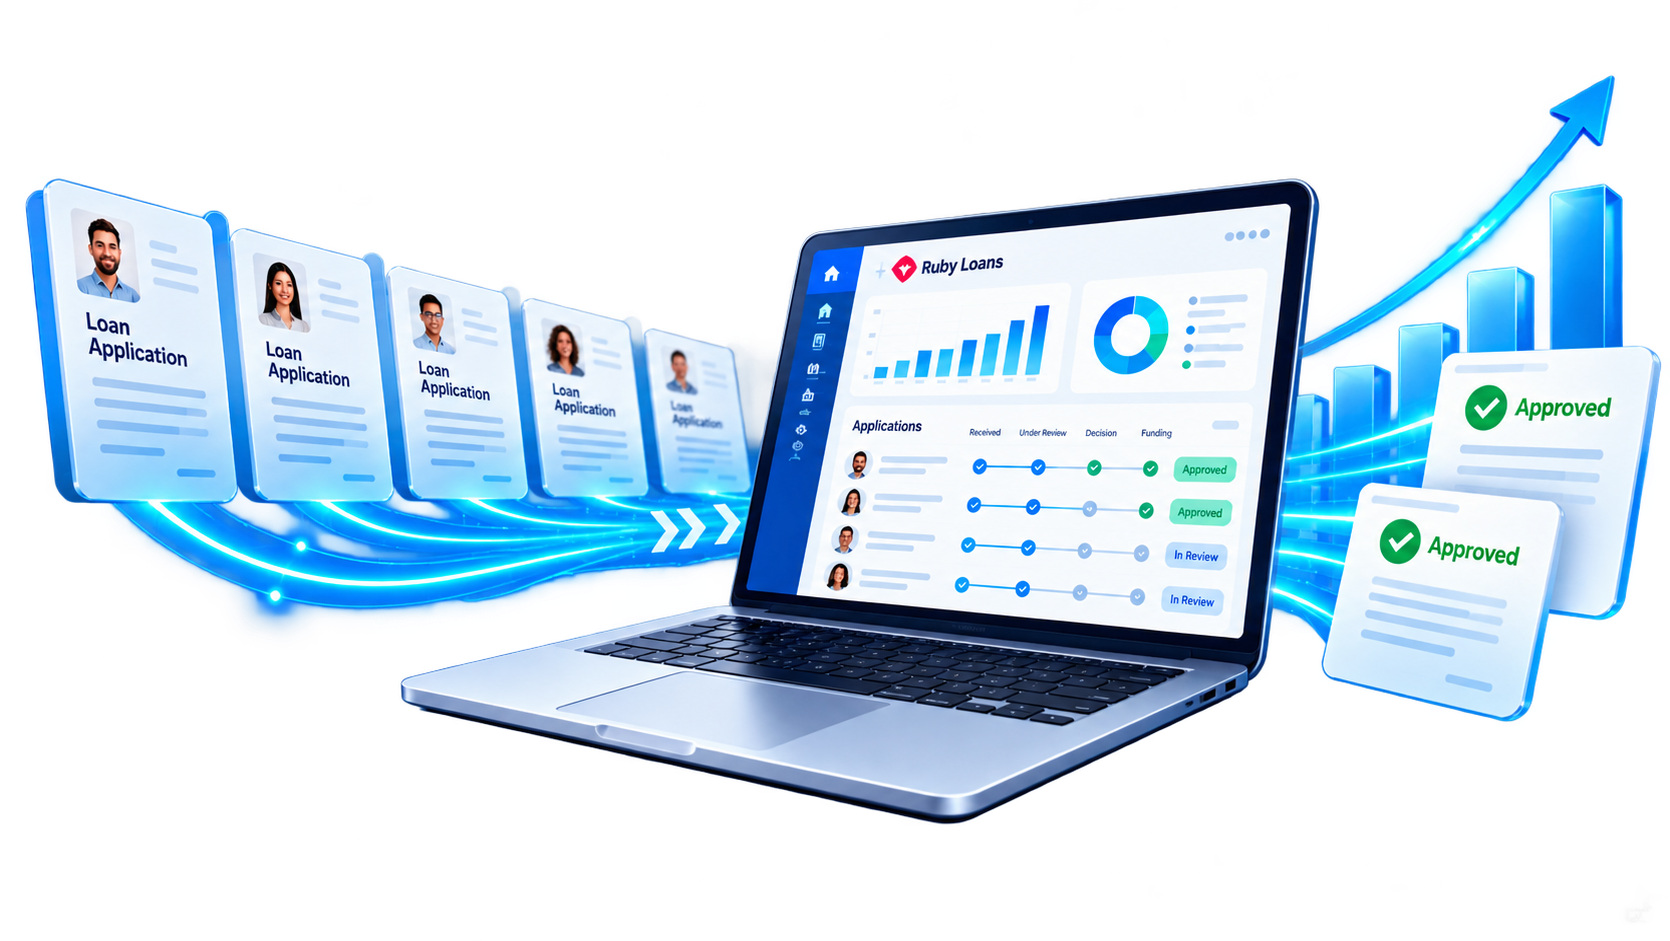
Ruby Loans standardizes how SME applications are gathered, assessed, and prepared so critical lending knowledge is embedded in the process rather than dependent on individual staff or informal practices
This supports continuity as teams change, strengthens lending discipline, and creates a more reliable process as SME portfolios grow
BOOK A DEMO